Hapag-Lloyd raises 2026 guidance as Q3 freight rates jump 28%
The 28% year-on-year increase in average freight rate, against flat volumes, accounts for the entire EBITDA improvement.
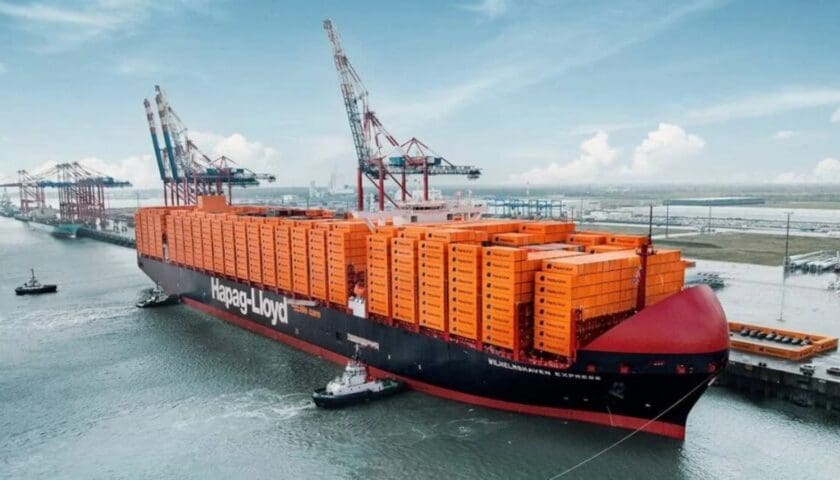
GERMANY – Hapag-Lloyd has raised its 2026 earnings outlook after reporting third-quarter figures of US$1.7 billion in Group EBITDA, US$1.1 billion in Group EBIT and US$1.0 billion in Group profit, according to a company statement.
The Executive Board decided on 11 November to increase full-year guidance to a Group EBITDA range of US$4.6-5.0 billion and a Group EBIT range of US$2.0-2.4 billion.
Revenue, rates and unit cost pressures
Liner Shipping revenue increased to US$6.7 billion, driven by an average freight rate of US$1,808 per TEU, up from US$1,413 per TEU in the third quarter of 2025.
Transport volumes reached 3.4 million TEU, in line with the prior-year quarter, despite the Middle East conflict and weather-related operational disruptions, both of which also put pressure on unit costs.
Terminal and Infrastructure revenue increased to US$197 million, reflecting investment in new and existing terminal capacity and improved performance across Latin American terminals.
Meanwhile, segment EBITDA rose to US$56 million and EBIT to US$34 million.
Rolf Habben Jansen, CEO of Hapag-Lloyd, said: “We delivered a strong third quarter, driven by significantly higher spot rates, robust demand and high capacity utilization. At the same time, unit costs still remain under pressure due to geopolitical tensions and operational disruptions.”
Guidance and market volatility
Business performance in the fourth quarter is developing better than previously expected, supported by continued robust spot freight rates.
However, the outlook remains subject to considerable uncertainty given volatile freight rates and persistent geopolitical challenges.
The 28% year-on-year increase in average freight rate, against flat volumes, accounts for the entire EBITDA improvement.
As a result, Hapag-Lloyd earned more per container rather than by carrying more containers, meaning the result is rate-dependent rather than volume-dependent.
In addition, the US$400 million guidance range between the EBITDA floor and ceiling reflects that dependency.
Moreover, if spot rates soften in the fourth quarter, results move towards the lower end; if Red Sea disruption and Asian congestion continue to absorb capacity, results hold near the top.
Ultimately, Hapag-Lloyd’s ability to sustain the upgraded outlook therefore rests less on its own operational performance than on market conditions that have kept rates elevated despite new vessel deliveries entering service through 2027.
Sign up HERE to receive our email newsletters with the latest news and insights from Africa and around the world, and follow us on our WhatsApp channel for updates.